
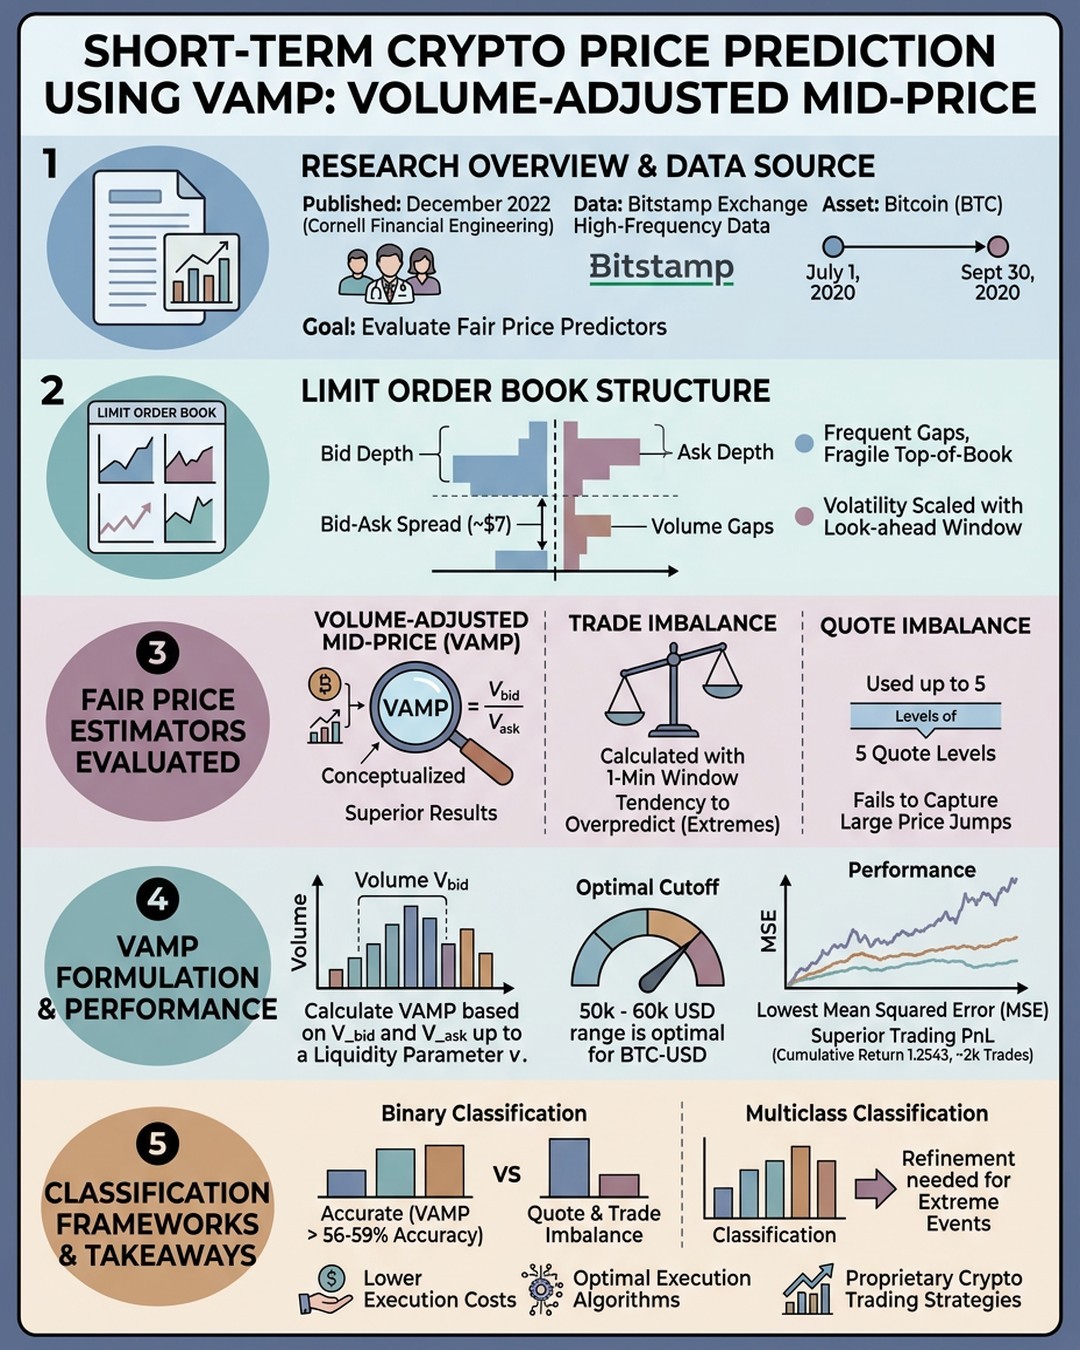
🔹 Research Overview and Data Source
【📌 Core Finding】Presented in December 2022 by Cornell Financial Engineering Manhattan researchers Payton Martin, William Line Jr., Yuxin Feng, Yunfan Yang, Sharon Zheng, Susan Qi, and Beiming Zhu with faculty advisor Sasha Stoikov. 【🔸 Data Source】Utilized high-frequency limit order book tick data and trading data from Bitstamp crypto exchange covering July 1, 2020, to September 30, 2020. 【⭐ Objective】Construct and evaluate mid-price adjustment estimators to define a robust fair price predictor for Bitcoin short-term price movements.