Short-term Crypto Price Prediction Using Volume-Adjusted Mid-Price

cornell-university financial-engineering cryptocurrency-prediction limit-order-book volume-adjusted-mid-price bitcoin-analysis

Samenvatting

Mindmap Omslagafbeelding
AI Gegenereerde Omslagafbeelding

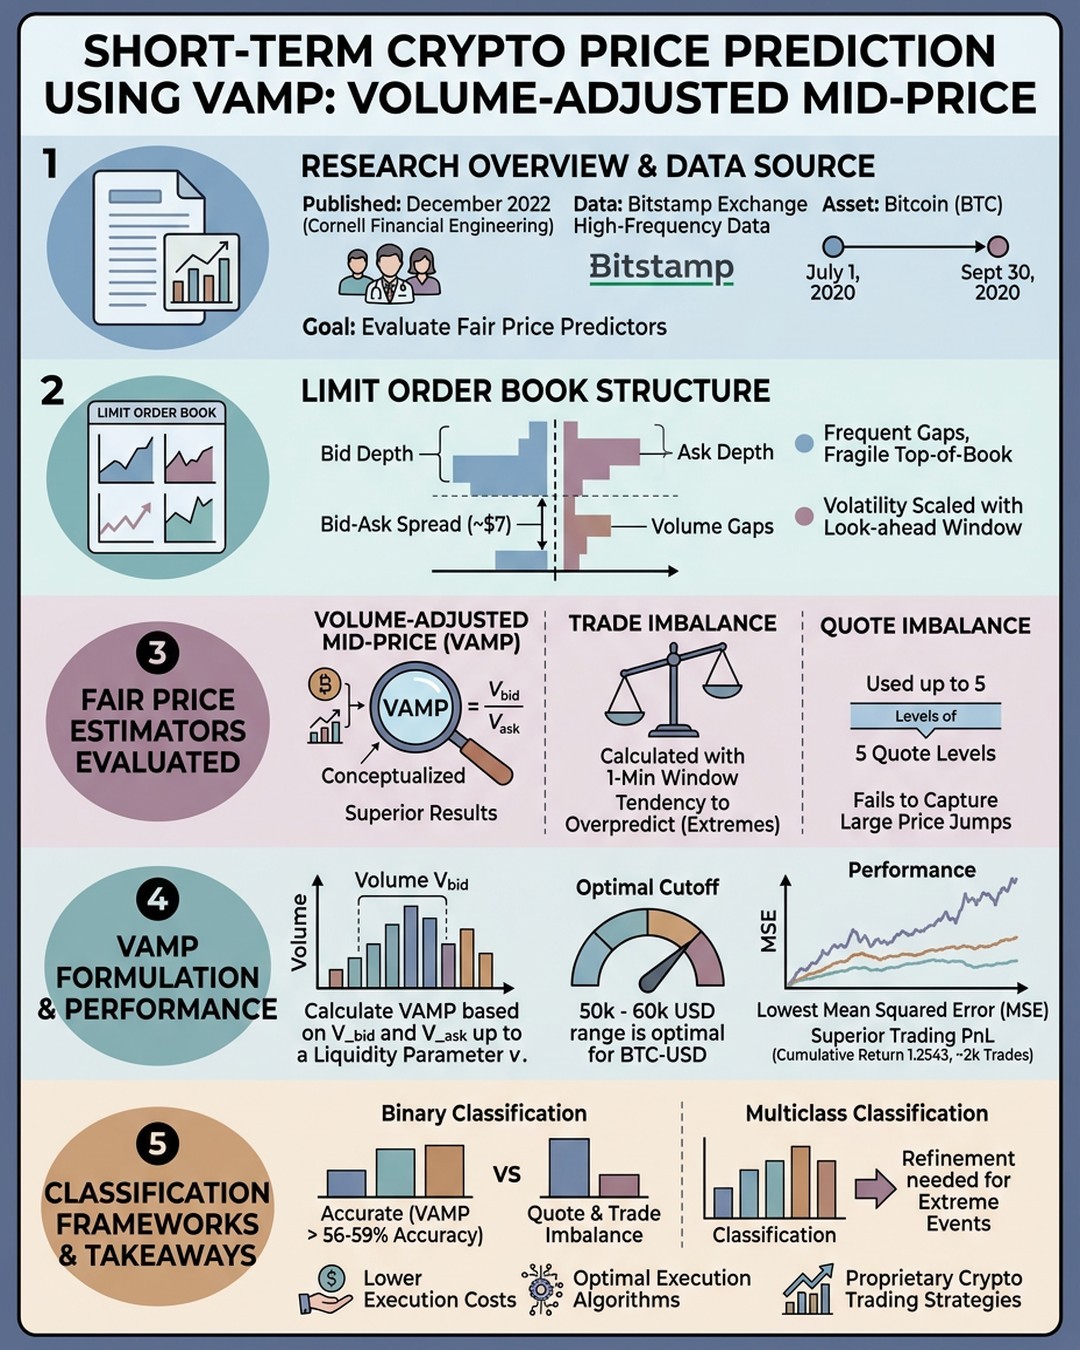
This research paper published in December 2022 by Cornell University financial engineering students explores short-term cryptocurrency price prediction using high-frequency limit order book data from Bitstamp for Bitcoin from July 1, 2020, to September 30, 2020. The authors evaluate three mid-price adjustment estimators including Volume-Adjusted Mid-Price, trade imbalance, and quote imbalance to determine a fair price estimator for Bitcoin. The authors demonstrate that the Volume-Adjusted Mid-Price outperforms trade and quote imbalance adjusted mid-prices in predicting both short-term price direction and larger one standard deviation price movements across multiple time windows ranging from 1 second to 60 seconds. The research utilizes preliminary metrics such as volatility, mean-squared error, and trading PnL alongside binary and multiclass classification frameworks. The core finding establishes that Volume-Adjusted Mid-Price with an optimal liquidity cutoff of 50,000 to 60,000 dollars captures liquidity pressure effectively from gaps in the fragile cryptocurrency order book. While trade imbalance tends to overpredict price movements and quote imbalance remains too close to the mid-price, Volume-Adjusted Mid-Price achieves an average binary classification accuracy ranging from nearly 59 percent down to 56 percent. Practical applications of this research include lowering execution costs, developing optimal execution algorithms, and implementing proprietary trading strategies in cryptocurrency markets. Future work suggested by the authors includes expanding data breadth to capture extreme crypto crash conditions and generalizing the Volume-Adjusted Mid-Price model to other asset classes.

Belangrijke punten

01

🔹 Research Overview and Data Source

【📌 Core Finding】Presented in December 2022 by Cornell Financial Engineering Manhattan researchers Payton Martin, William Line Jr., Yuxin Feng, Yunfan Yang, Sharon Zheng, Susan Qi, and Beiming Zhu with faculty advisor Sasha Stoikov. 【🔸 Data Source】Utilized high-frequency limit order book tick data and trading data from Bitstamp crypto exchange covering July 1, 2020, to September 30, 2020. 【⭐ Objective】Construct and evaluate mid-price adjustment estimators to define a robust fair price predictor for Bitcoin short-term price movements.

02

🔸 Limit Order Book Structure and Characteristics

【📌 Market Microstructure】Cryptocurrency order books exhibit frequent and inconsistent gaps where no volume is present, making the top-of-the-book fragile compared to equity markets. 【🔸 Spread and Price Changes】The bid-ask spread persisted around 7 dollars, while the 60-second average price change for Bitcoin remained less than 4 dollars with a standard deviation of 7 dollars. 【⭐ Volatility Scaling】Both average price change and standard deviation of price movements increase proportionally with the square root of the look-ahead window.

03

⭐ Three Fair Price Estimators Evaluated

【📌 Model Candidates】Analyzed Volume-Adjusted Mid-Price, trade imbalance adjusted mid-price, and quote imbalance adjusted mid-price. 【🔸 Trade Imbalance】Calculated using 1-minute trailing window with linear weights, but tended to overpredict due to heavy dominance at extremes -1 and 1. 【⭐ Quote Imbalance】Defined using up to 5 levels of quote data, but MSE optimization caused it to stay too close to the mid-price, failing to capture large price jumps.

04

📊 Volume-Adjusted Mid-Price Formulation and Performance

【📌 VAMP Definition】Calculated using volume-weighted bid and ask prices where summed volume equals liquidity parameter v. 【🔸 Optimal Cutoff】Determined that a liquidity cutoff in the 50,000 to 60,000 dollar range performs best for the Bitstamp BTC-USD market. 【⭐ Superior Results】VAMP achieved the lowest mean-squared error at 30 and 60-second windows and dominated trading PnL with a cumulative return of 1.2543 across 1,973 trades.

05

💡 Classification Frameworks and Practical Takeaways

【📌 Binary Classification】VAMP achieved prediction accuracy ranging from over 59 percent to just under 56 percent, outperforming quote imbalance and trade imbalance. 【🔸 Multiclass Classification】Evaluated one standard deviation large price movements, showing VAMP as superior in precision though requiring refinement for extreme events. 【⭐ Practical Applications】Findings can be applied to lower execution costs, build optimal execution algorithms, and power proprietary crypto trading strategies.

Wilt u uw eigen mindmap maken?

Log in op Neumap AI en begin met het maken van uw eigen mindmaps!

Aan de Slag